Modern Malaysian home with the Kuala Lumpur skyline in the distance

Property calculator

Home Loan Calculator Malaysia

Estimate monthly repayment, total interest and how optional extra payments may change your loan.

Your details

Enter your figures

Examples appear as placeholders only. Enter your own values to calculate.

Advanced optionsOptional

Your entries stay in this browser and are not stored.

PrivateRuns locallyInstantFast resultsClearVisual context

Your personalised estimate

Ready when you are

Enter your figures and calculate to reveal the result, clear charts, yearly detail and personalised tips.

Visual breakdownDesigned PDF

Home loan basics

How Are Home Loan Repayments Calculated in Malaysia?

Home loan repayments in Malaysia are typically estimated using the amount financed, the effective annual interest or profit rate, and the loan tenure.

For a reducing-balance loan, each monthly payment covers interest on the outstanding balance and a portion of the principal. As the outstanding balance falls, more of each payment generally goes towards principal.

A larger loan amount or higher interest rate increases the monthly repayment. A longer tenure usually reduces the monthly commitment, but can increase the total interest paid over the life of the loan.

Your actual instalment depends on the rate and terms offered by your bank. Use the effective rate from your Letter of Offer or product quotation whenever possible.

Understand more

How Our Home Loan Calculator Helps You

Get a clearer picture of your home loan, compare scenarios and make more informed property decisions.

  1. 1
    Enter Your Details

    Property price, down payment, effective rate and loan tenure.

  2. 2
    We Do the Calculation

    Apply monthly reducing-balance interest and principal repayments.

  3. 3
    View Your Results

    Compare instalment, total interest and the full yearly breakdown.

  4. 4
    Try Different Scenarios

    Adjust the tenure, deposit or extra payment and compare the cost.

Simple and transparent

How this calculator works

Malaysian Calculator divides the annual rate entered by 12 to obtain a monthly rate and applies a standard reducing-balance amortisation formula. The property price less your down payment gives the starting loan amount. Entered purchase costs are added only if you select the option to finance them.

The monthly repayment is calculated so the outstanding loan balance reaches approximately zero at the end of the selected tenure, assuming the entered interest rate remains unchanged and payments are made as scheduled. Optional extra payments are applied after monthly interest is charged.

Monthly repayment formulaM = P × [r(1+r)ⁿ] / [(1+r)ⁿ − 1]
  • M = estimated monthly repayment
  • P = amount financed
  • r = monthly interest rate (annual rate ÷ 12)
  • n = number of monthly repayments

This formula provides an estimate. Actual bank calculations may differ slightly because of daily interest calculations, rounding, disbursement timing, rate changes or product-specific terms. At a zero interest rate, the base payment is simply the amount financed divided by the number of months.
Realistic example

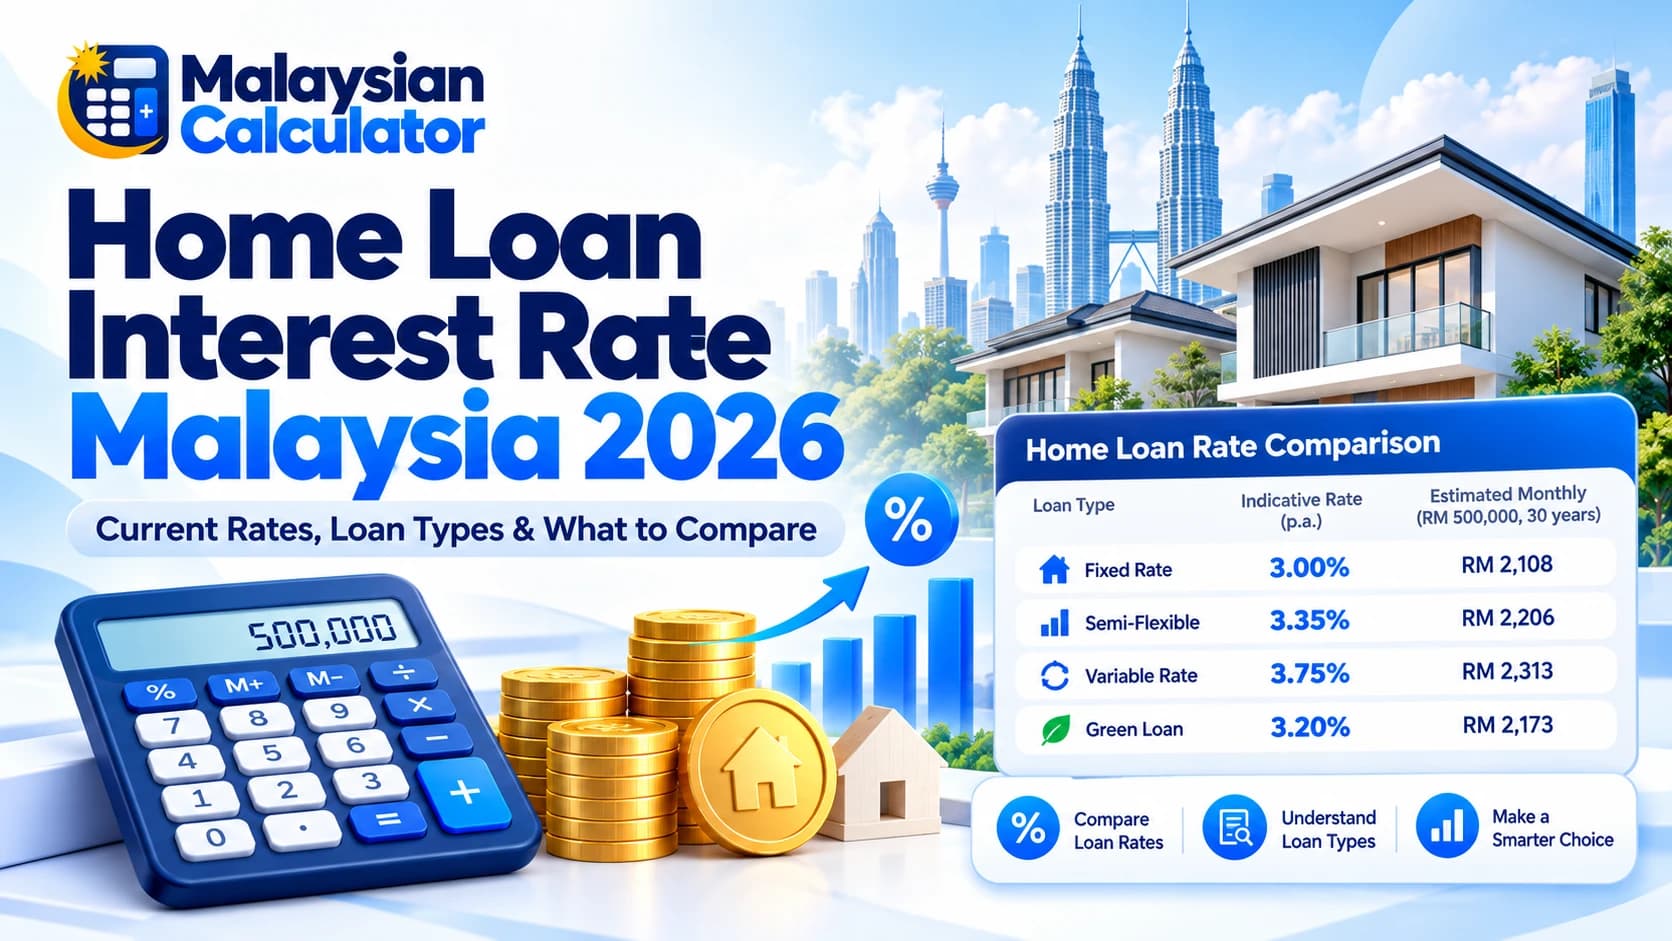
Example: RM500,000 Home Purchase in Malaysia

The scenario

Property price
RM500,000
Down payment
RM50,000
Estimated loan amount
RM 450,000
Example effective rate
4.15% p.a.
Loan tenure
35 years

The result

Estimated monthly repaymentRM 2,033Calculated by the same engine as the tool above
Estimated total interest
RM 403,934
Estimated total repayment
RM 853,934

This example shows why monthly repayment should not be the only figure you compare. Extending the tenure can make the monthly instalment easier to manage, but it also gives interest more time to accumulate.

Try reducing the tenure or adding an extra monthly payment in the calculator above to see how the total financing cost changes. Compare the full yearly schedule as well: early payments contain more interest, while later payments repay more principal.

Illustration only. The example assumes the entered rate remains unchanged throughout the loan period and excludes additional purchase costs.

Malaysia rate reference

Understanding OPR, SBR and Your Home Loan Rate

Since 1 August 2022, the Standardised Base Rate (SBR) has been the common reference for new retail floating-rate loans and financing. It moves solely with Bank Negara Malaysia’s Overnight Policy Rate (OPR).

Your final home-loan rate is not simply the OPR or SBR. Banks add a spread that reflects the product, borrower’s credit risk, liquidity considerations, operating costs and other pricing factors. Existing facilities may still refer to BR or BLR; check the reference named in your own offer.

Current BNM OPR
2.75%
BNM Overnight Policy Rate
Standardised Base Rate
2.75%
SBR = BNM OPR
Your actual home-loan rate
SBR + bank/product spread
Use the effective rate in your bank quote
Bank Negara Malaysia · Reference decision: · Last checked: Official source
Example onlyThis is arithmetic to explain the spread, not a bank quotation or a rate available to everyone.

SBR2.75%Illustrative bank spread1.15%Illustrative effective rate3.90%

What changes the result

What Affects Your Home Loan Repayment?

Five inputs move your instalment and the total cost. Change one at a time in the calculator to see its effect.

Loan amount

The more you finance, the higher the monthly commitment and total interest.

Interest / profit rate

A higher effective rate increases the cost of financing.

Loan tenure

Longer tenure can reduce the monthly payment but increase total interest.

Down payment

A larger down payment reduces the amount financed.

Extra repayments

Additional principal payments may reduce interest and shorten the effective repayment period, depending on the loan terms.

Before you decide

Common Home Loan Calculation Mistakes

Five assumptions that most often make an estimate look different from the loan a bank actually offers.

  1. Using the OPR as your home loan rate

    OPR affects the SBR, but the final rate offered by the bank includes a product/customer spread.

  2. Comparing only the monthly instalment

    A longer tenure can reduce monthly repayment while increasing the total financing cost.

  3. Assuming the maximum tenure is automatically better

    The most comfortable monthly payment is not always the lowest-cost option.

  4. Confusing repayment with eligibility

    A repayment calculator estimates how a loan may be repaid. It does not determine whether a bank will approve the loan.

  5. Forgetting upfront ownership costs

    Your property budget may also need to cover the down payment, stamp duty, legal fees, valuation, insurance/takaful and other costs.

Know the scope

What This Home Loan Calculator Includes

Included

  • Estimated monthly repayment
  • Estimated loan amount
  • Estimated total interest
  • Estimated total repayment
  • Loan balance over time
  • Principal vs interest
  • Yearly breakdown
  • Optional extra monthly payment
  • Optional user-entered upfront costs

Not automatically included

  • Bank approval
  • Credit assessment
  • Exact DSR eligibility
  • Future interest-rate changes
  • Exact MRTA/MRTT quotation
  • Bank-specific fees
  • Exact legal fees unless entered
  • Exact stamp duty unless entered
  • Product-specific lock-in / redraw rules

Use the related calculators for affordability, DSR, stamp duty, property legal fees and refinancing. Upfront costs affect the cash-needed figure unless you explicitly finance them; adding a cash cost alone does not change the loan instalment.

Sources & methodology

Where This Information Comes From

The worked example uses the same home-loan engine as your calculation above, including monthly interest and principal allocation. Results are rounded for display; the engine keeps calculation precision while producing the repayment schedule.

Official sources establish the reference-rate relationship, not your personal bank quote. The dated OPR record is reviewed manually and maintained in our source and rate records. Product terms should be checked in the lender’s disclosure sheet. This page is not connected to a live bank pricing feed.

Home loan results are estimates for planning. Actual rates, approval, margin of financing, repayment and product terms depend on the lender and your circumstances.

Next calculation

Related calculators

Property

Stamp Duty Calculator

Estimate property transfer duty and optional loan-agreement duty using a clear tier breakdown.

→

Common questions

Home Loan Calculator FAQ

Quick answers to the questions people usually ask before relying on an estimate.

Spotted something outdated?

Tell us which figure or rule looks wrong so it can be checked against the official source.

Most Malaysian home loans are calculated on a reducing-balance basis. The estimated monthly instalment depends mainly on the loan amount, effective annual interest/profit rate and total number of monthly repayments. Your bank’s actual repayment may differ because of product terms, rate changes, fees or rounding.