Enter your figures and calculate to reveal the result, clear charts, yearly detail and personalised tips.
Visual breakdownDesigned PDF
The quick answer
How Is Fixed Deposit Interest Calculated in Malaysia?
Reviewed against official sources · 11 October 2026
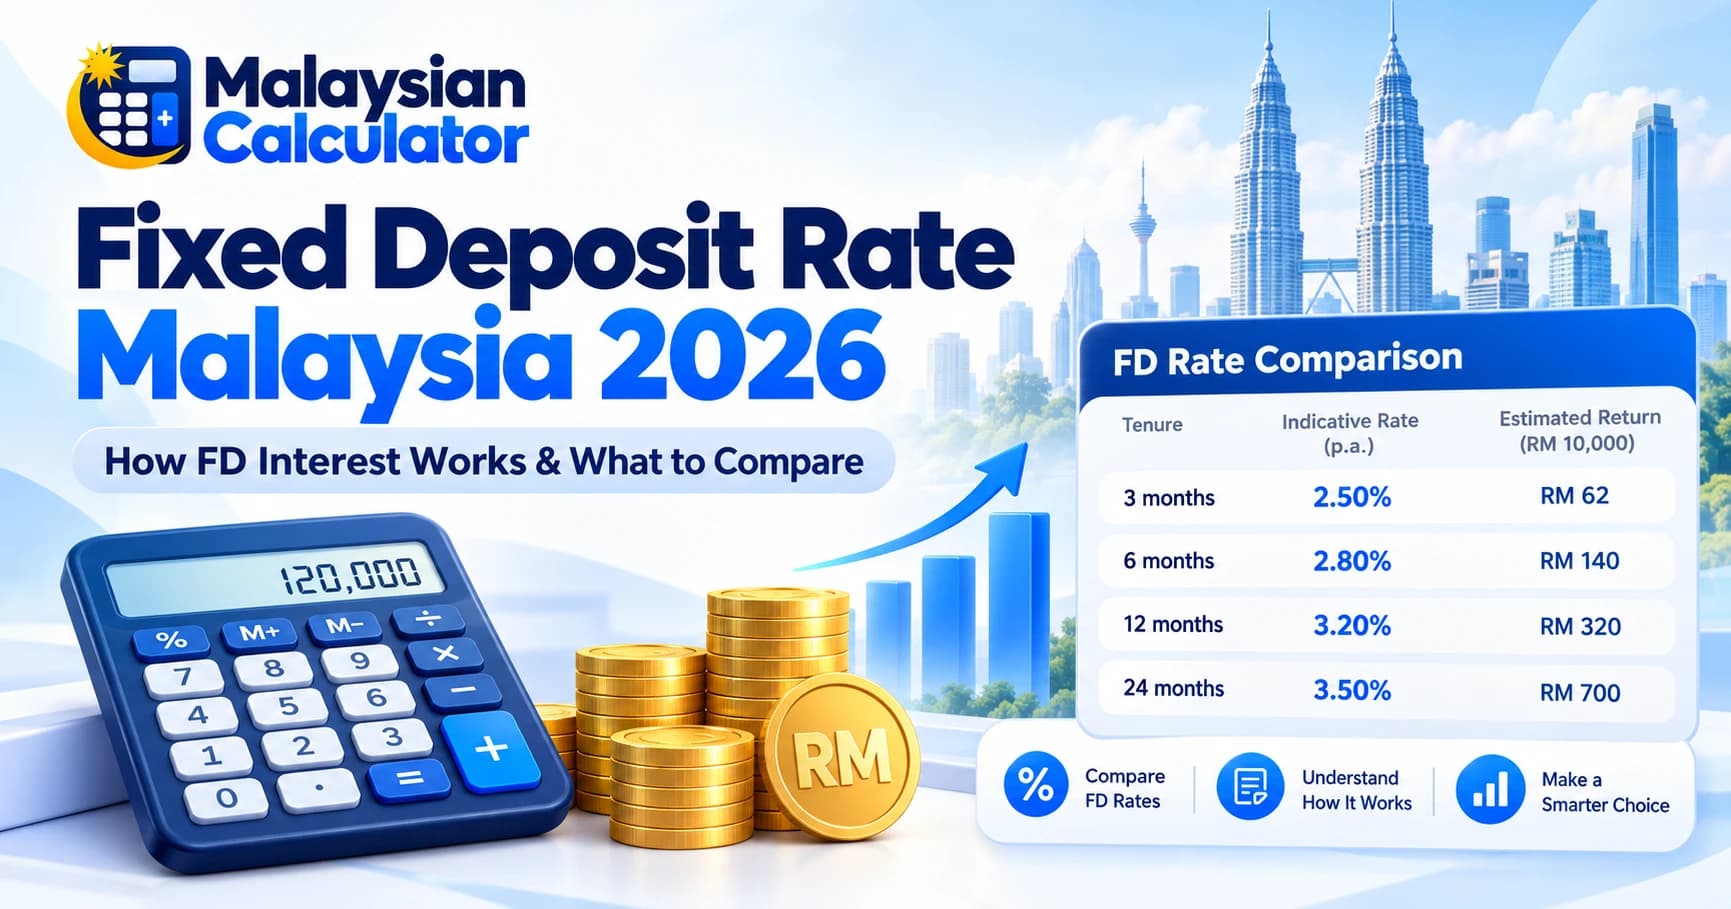
Fixed deposit interest in Malaysia is simple interest: deposit × annual rate × the fraction of the year. A 12-month placement of RM20,000 at 2% earns RM400 at maturity.
Rates differ by bank and tenure. Board rates at major banks were around 1.75% to 2.05% a year in mid-2026; promotional rates can be higher but often need fresh funds or a minimum amount.
Fixed deposits with licensed banks are protected by PIDM up to RM250,000 per depositor per bank, including interest. FD interest earned by individuals from licensed banks is generally exempt from income tax.
Withdrawing before maturity usually means losing the interest. At Maybank, for example, early withdrawal without notice earns nothing.
Understand more
Understand fixed-deposit returns
See principal, estimated interest and maturity value for the entered annual rate and placement term.
1
Enter the relevant figures
Enter the deposit amount, annual interest rate and placement term in months.
2
Apply the calculation
The calculator prorates the annual rate across the selected number of months and adds the estimated interest to the principal at maturity.
3
Read the main result
See principal plus estimated interest.
4
Compare a second scenario
Splitting funds across maturity dates can preserve liquidity instead of locking the full amount into one term.
Simple and transparent
How fixed deposit is calculated
The calculator prorates the annual rate across the selected number of months and adds the estimated interest to the principal at maturity.
The return depends on deposit amount, annual rate, placement period and the bank’s interest/profit calculation and payout method. Enter the exact promotional or board rate for the tenure you are considering.
Promotions can have conditions such as minimum fresh funds, specific placement channels, bundle requirements or limited campaign periods. Always check the terms before treating a promotional rate as generally available.
It depends on the product and tenure. Some deposits pay at maturity while others may offer periodic interest/profit payments.
Early withdrawal can reduce or eliminate the interest/profit you would otherwise receive, depending on the bank’s terms and how the placement is structured.
Many fixed deposits quote a simple annual rate for the placement period, but products with periodic reinvestment or rollover can create a compounding effect. Use the product’s actual payout/reinvestment method.
Eligible deposits placed with PIDM member banks are protected subject to PIDM’s prevailing eligibility rules and coverage limits. Confirm that the specific bank and product qualify.
Compare the effective return for the same amount and tenure, together with conditions, payout timing, early-withdrawal terms and whether the promotional rate applies to your funds.